
You're closing December. The crew finished the job, the customer hasn't paid, and your bookkeeper wants to know which month gets the sale. Meanwhile, subcontractor bills and payroll will clear the bank after year-end. Which year gets the revenue and the cost, and how much of that profit can you spend?
A useful example of accrual basis accounting answers both questions. It separates the work date, the invoice date, and the cash date, so you can measure performance without mistaking an unpaid invoice for money in the bank.
Table of Contents
- The Question an Accrual Example Should Answer
- Accrual Entry Categories Owners Actually Use
- Journal Entries for the Core Accrual Cases
- Recognition Tests Before You Book the Amount
- December Project Walkthrough on the Statements
- Inventory Deposits and Month End Cutoff
- Profit on Paper While the Bank Balance Falls
- Work Performed Versus Invoice Versus Cash
- Quick Reference Chart and Cross Links
- Pair the Close With a Cash Forecast
The Question an Accrual Example Should Answer
Say a contractor completes a $250,000 project and earns the right to bill on December 20, 2025, but the customer pays on February 15, 2026. Subcontractor and material costs of $150,000 belong to December, although suppliers receive payment in January. The project produces $100,000 of gross profit and a 40% gross margin in 2025, before considering other business expenses.
The invoice's actual issue date still belongs in the close file. Earning the right to bill doesn't prove that someone sent the invoice that day. That distinction matters operationally: work can be profitable while an administrative delay postpones collection.
What the accounts mean
Accrual basis accounting records revenue when it's earned and expenses when they're incurred, subject to the applicable recognition rules. It doesn't wait for the bank transaction.
The accounts between performance and payment make that timing visible:
- Accounts receivable represents money the business has earned an unconditional right to collect but hasn't collected yet.
- Accounts payable records supplier obligations, generally supported by bills received but not paid.
- Accrued liabilities capture obligations such as earned payroll or completed vendor services awaiting billing.
- Deferred revenue records customer payments received before the related work is earned.
Owner's rule: Ask what happened economically before asking what cleared the bank.
The management benefit is straightforward. You can judge the job's pricing and delivery separately from the customer's payment behavior.
Keep the journal-entry table beside your close checklist. Use the categories to select an entry, the recognition tests to validate it, and the statement walkthrough to check its effect. The cutoff examples and cash bridge help you catch the two mistakes owners can least afford: overstated margins and unexpected cash shortages.
Accrual Entry Categories Owners Actually Use
Start by sorting the transaction, not by choosing a debit. Construction, distribution, and professional-services businesses encounter different documents, but the underlying timing questions are similar.
The visual distinguishes earned amounts awaiting billing from earned amounts awaiting payment.
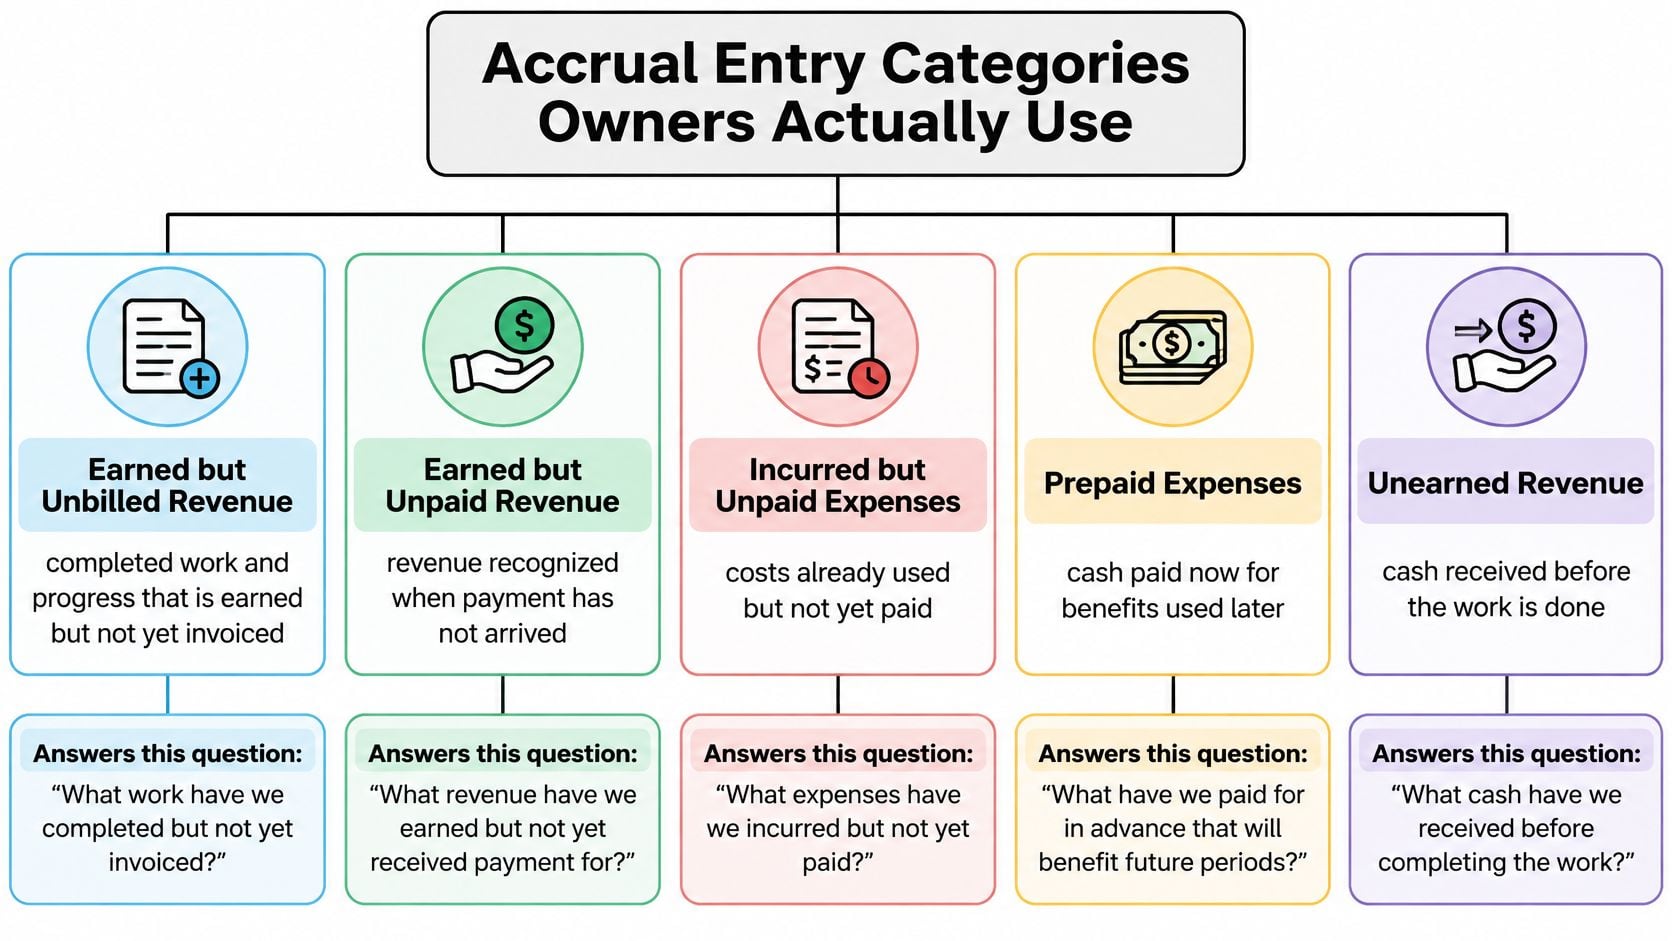
Sort the transaction before posting
Earned but unbilled or unpaid revenue answers: Have we delivered something we're entitled to recognize? Specialty trades may complete measurable progress before a billing milestone. A professional-services firm may finish an assignment before the customer pays. Whether the asset is a receivable or a contract asset requires a separate review of payment rights.
Incurred but unpaid costs answers: What resources did we already use? Payroll days worked, completed subcontractor services, and freight on delivered goods belong in this review. Waiting for a vendor's invoice can make a job look more profitable than it is.
Prepaid and deferred items answer: Did cash move before the benefit was used or the work was earned? Insurance paid ahead creates an asset that becomes expense as coverage is consumed. A customer deposit creates an obligation until the business performs.
Two more categories prevent unnecessary income-statement entries:
- Balance-sheet-only receipts: A distributor receiving inventory on supplier terms usually records an asset and a payable. Receipt isn't automatically cost of goods sold.
- Items that aren't accruals yet: An unsupported change order, a vendor's preliminary estimate, or work nobody has performed needs investigation, not an automatic journal entry.
Documents support the entry, but don't decide it
An invoice is a billing document. It helps establish the amount and payment terms, but it doesn't independently establish that revenue has been earned.
A bank withdrawal also doesn't prove an expense belongs in that month. The payment might settle an old payable, purchase inventory, or prepay a future benefit.
Choose the category first. Then select the matching journal-table row and document the work date, billing status, and settlement date separately.
Journal Entries for the Core Accrual Cases
| Case | Debit | Credit | Amount | What the books show |
|---|---|---|---|---|
| Construction earned Dec 20 2025, paid Feb 15 2026 | Accounts receivable | Revenue | $250,000 | 2025 income, cash in 2026 |
| December costs paid in January 2026 | Cost of goods sold or WIP | Accounts payable | $150,000 | 2025 cost; $100,000 gross profit, 40% margin when expensed |
| Half of a $120,000 contract done by Dec 31 | Unbilled receivable | Revenue | $60,000 | Only the earned half |
| $30,000 project accepted in December, paid in January | Accounts receivable | Revenue | $30,000 | January cash clears the receivable |
| December labor of $8,000 paid in January | Compensation expense | Accrued payroll | $8,000 | December margin on that job is $22,000 |
| Inventory received in December, net 30 | Inventory | Accounts payable | $120,000 | Balance sheet only until sold |
| Customer deposit before any work | Cash | Contract liability | $200,000 | Cash up, no revenue yet |
| Vendor estimate, liability not fixed | Do not record | Do not record | $20,000 estimate, no entry | Wait for a fixed liability, reliable amount, and performance |
Example of accrual basis accounting journal entries. These are separate scenarios, not entries to combine into one company's ledger.
Copy the relevant row into the period supported by the underlying activity. The IRS guidance on business accounting methods generally places earned income and incurred costs in their proper year, illustrated here by the construction project's $250,000 revenue, $150,000 associated costs, and $100,000 gross profit at a 40% margin.
How to read the debits and credits
A debit or credit is an entry's accounting direction, not a synonym for good or bad. In these examples, debits increase assets or expenses, while credits increase revenue or liabilities.
For the completed construction project, debit receivables and credit revenue when the billing right is established. Record the invoice issue date independently; when payment arrives, debit cash and credit receivables.
The matching subcontractor and material entry debits cost of goods sold, meaning the direct costs associated with recognized sales. Work in progress, or WIP, is an asset for eligible costs still carried on an unfinished job. Don't treat these alternatives as interchangeable: a cost remaining in WIP hasn't yet reduced gross profit.
For the partially completed services contract, recognize only the earned portion when the reporting rules support recognition over time. Use an unbilled receivable only if that classification fits the contractual rights; otherwise, a contract asset may be appropriate.
Separate earning entries from settlement entries
The accepted professional-services project creates receivables and revenue in December. The January customer deposit into the bank increases cash and reduces receivables. It doesn't create another sale.
December labor creates compensation expense and accrued payroll, the liability for employee work already performed. Payday reduces that liability and cash, rather than charging the same labor to expense again.
Inventory receipt increases inventory and accounts payable. A customer advance increases cash and a contract liability, the obligation to deliver work or goods. Neither entry creates immediate profit.
The vendor estimate gets no entry under the stated facts. A quote alone doesn't establish a completed service or a fixed obligation.
Use this posting order at close:
- Recognize earned revenue supported by performance and contractual rights.
- Accrue payroll for employee time already worked.
- Capture uninvoiced vendor work supported by completed activity.
- Post cash settlements against the existing receivables and liabilities.
Check for duplicate entries before posting a later invoice. Otherwise, the accrual and the bill can charge the same cost twice.
Recognition Tests Before You Book the Amount
An accrual isn't permission to record whatever management expects. The entry needs evidence of an earned right or an incurred obligation, a supportable amount, and the relevant performance.
Use this checklist as a gate before posting.
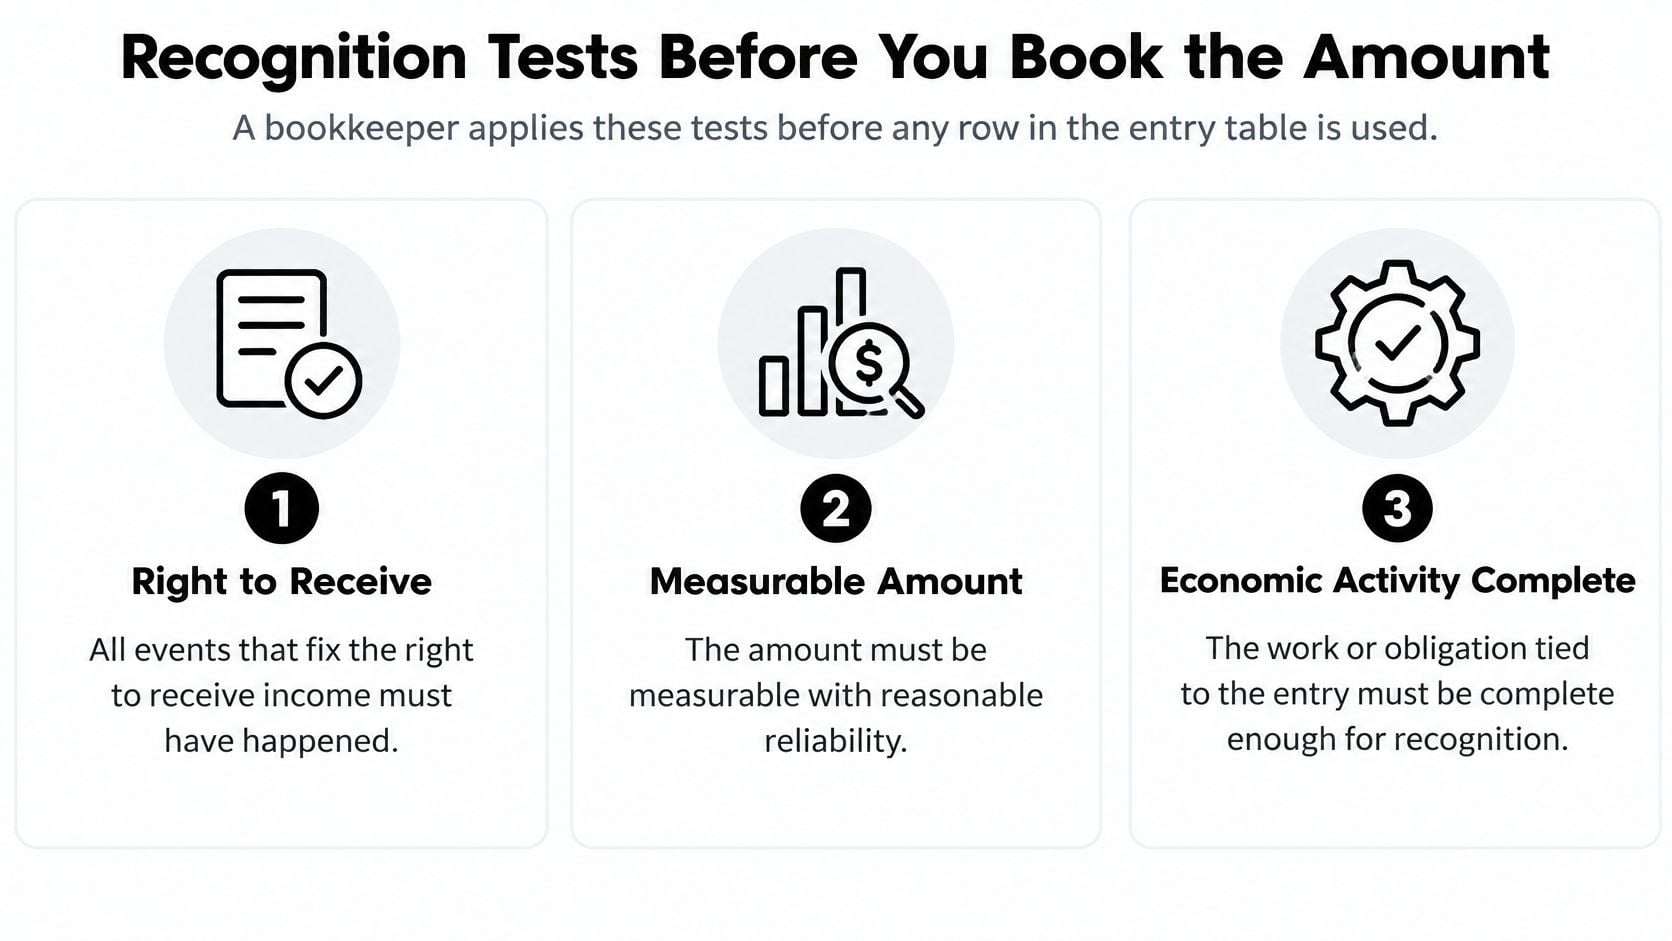
Apply the tests to the transaction
For federal tax accrual accounting, IRS Publication 334 generally requires income recognition when all events fixing the right to receive it have occurred and the amount is reasonably determinable; in the services scenario, a $120,000 contract signed November 1, 2025, with 50% earned by December 31, supports $60,000 of revenue when reliably measured.
Keep the dates distinct. Signing establishes the agreement, performing establishes the earned amount, invoicing documents the billing, and payment settles collection. The expected January cash receipt doesn't determine the earned portion.
For expenses, ask whether the liability is fixed and measurable and whether economic performance has occurred. In owner language, purchased services generally satisfy that performance requirement as the vendor provides them, subject to the applicable tax rules.
A $20,000 vendor estimate fails this gate if there's no fixed liability or the service hasn't been performed. Don't confuse a supportable estimate of completed work with a quote for future work.
For additional plain-language context, Bookkeeping and Accounting of Florida Inc.’s guide to understanding revenue recognition for small businesses helps connect delivery obligations to recognition decisions.
Run a documented close routine
- Record qualifying revenue. Attach performance evidence, contractual rights, and the calculation.
- Accrue earned payroll. Use approved time records through the reporting cutoff.
- Capture completed vendor work. Include subcontractors and freight even when invoices haven't arrived.
- Reverse or settle estimates. Match subsequent bills against accruals and explain differences.
A hoped-for change order isn't automatically earned revenue. Pulling future costs into the current month is equally misleading, even if management prefers the resulting comparison.
Keep a book-to-tax differences list for your CPA. Financial-reporting recognition and tax deduction rules aren't identical, so don't erase a sound book entry merely to force agreement with the tax return.
For an additional explanation of accrual timing, use this video alongside the checklist.
December Project Walkthrough on the Statements
Follow a single professional-services job through performance, billing, and collection. The firm completes the work and the customer accepts it in December; payment arrives in January. Record the invoice issue date from the actual billing record rather than assuming acceptance and invoicing happened together.
Under the economic-period approach described in FASB's conceptual framework, this $30,000 accepted project and its $8,000 of December employee work produce $22,000 of December gross profit, assuming that labor is classified as a direct project cost.
December measures the work
Post the customer-side entry when the revenue is earned and the receivable criteria are met. Post the payroll accrual for employee work performed through month-end.
| December entry | Debit | Credit |
|---|---|---|
| Recognize accepted project | Accounts receivable $30,000 | Revenue $30,000 |
| Recognize employee work | Compensation expense $8,000 | Accrued compensation $8,000 |
The income statement, which reports performance over a period, shows project revenue less direct compensation. That project contribution isn't necessarily the company's net income; rent, overhead, and other expenses may still need to be deducted.
The balance sheet, which reports assets and obligations at a point in time, shows the customer receivable and the payroll liability. Working capital means current assets less current liabilities. Here, the project's working-capital contribution is held in a receivable, not spendable cash.
The sequence makes the distinction visible.
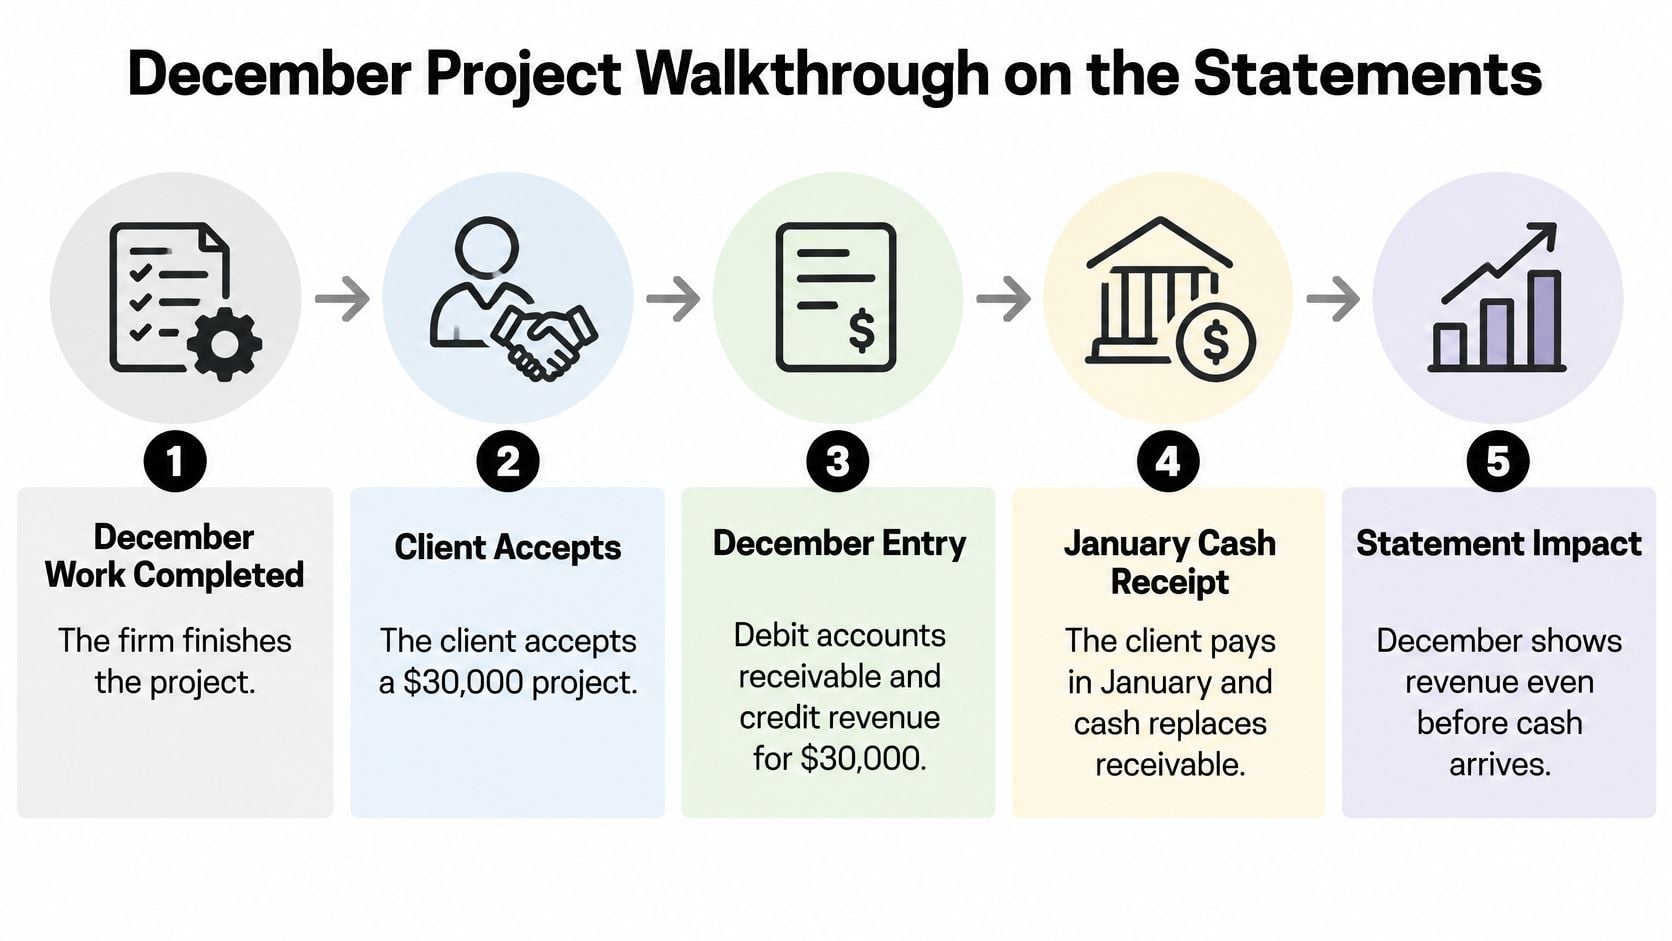
January settles the balances
| January entry | Debit | Credit |
|---|---|---|
| Collect customer payment | Cash $30,000 | Accounts receivable $30,000 |
| Pay December compensation | Accrued compensation $8,000 | Cash $8,000 |
January revenue from this completed job is zero. The receipt replaces the receivable with cash, and payday removes the compensation obligation. That's why reviewing the January bank feed alone would misidentify when the business performed the work.
Use a one-job worksheet
Fill this out for your largest open job before the next close. Add the actual invoice issue date beside the billed amount and record receipt or payment dates beside cash amounts.
| Work date | Amount earned | Amount billed | Amount collected | Cost incurred | Cost paid |
|---|---|---|---|---|---|
| Actual performance period | Supported earned value | Invoice amount and issue date | Receipt amount and date | Labor and vendor costs belonging to the work | Payment amount and date |
Complete the month-end tie-out with these checks:
- Unbilled receivables: Confirm recognized work hasn't disappeared because billing is late.
- Customer deposits and deferred revenue: Reconcile advances to remaining delivery obligations.
- Accrued payroll: Match unpaid employee time to the correct work period.
- Unreceived subcontractor invoices: Obtain progress support so missing bills don't inflate margin.
Skipping a cost can overstate profitability. Skipping earned work can understate it. Misclassifying deposits or receivables also leaves management with a working-capital report that doesn't describe what customers owe or what the business still must deliver.
Inventory Deposits and Month End Cutoff
Inventory receipts and customer deposits often create balance-sheet entries before they affect profit. Treating either as an immediate income-statement event can distort the month's results.
Using the accrual and economic-performance principles in IRS Publication 538, consider a distributor receiving $120,000 of inventory in December on net 30 terms, and a separate contractor receiving $200,000 of customer deposits before performing the work. These require different entries, even though both create obligations.
Receiving goods isn't the same as consuming them
The distributor debits inventory and credits accounts payable when the goods are received under the applicable ownership terms. Net 30 generally means the supplier expects payment within the agreed payment window, not that the inventory becomes an expense when paid.
The supplier invoice issue date should be recorded separately from the receiving date. When the distributor pays in January, it debits accounts payable and credits cash.
Profit generally changes when the inventory is sold, or when costs are otherwise consumed and recognized under the applicable policy. If materials move into a construction job, eligible costs may first move into WIP.
Use a schedule for cost of goods sold to reconcile inventory movements with the costs charged against revenue. For online sellers dealing with freight and other acquisition costs, Supply Automate's explanation of accurate inventory margins for e-commerce brands provides useful landed-cost context.
A deposit comes with a delivery obligation
The contractor debits cash and credits a contract liability or deferred revenue. Revenue follows the relevant performance, not the deposit receipt.
Record the work period, advance invoice date if applicable, and cash receipt date separately. A paid invoice can still represent an obligation to perform rather than an earned sale.
Test the reporting boundary
Cutoff means placing receipts, services, revenue, and costs in the reporting period where they belong. Review the last three business days of the month and the first three of the next month as a practical starting window, expanding it when billing or delivery delays warrant.
Build the support file around:
- Receiving reports: Match actual receipt and ownership evidence to supplier invoices.
- Subcontractor progress: Obtain documented completion status, not just a payment request.
- Freight support: Identify charges for goods already delivered.
- Deposit schedules: Tie customer advances to contracts and remaining work.
Goods received but not invoiced may require an accrual. An invoice for undelivered goods doesn't automatically justify recording inventory received; investigate ownership terms and any prepayment classification.
Purchased services generally satisfy economic performance as vendors provide them. Keep tax differences in a separate reconciliation. Your margins and inventory values shouldn't swing merely because someone pays a supplier on the 10th.
Profit on Paper While the Bank Balance Falls
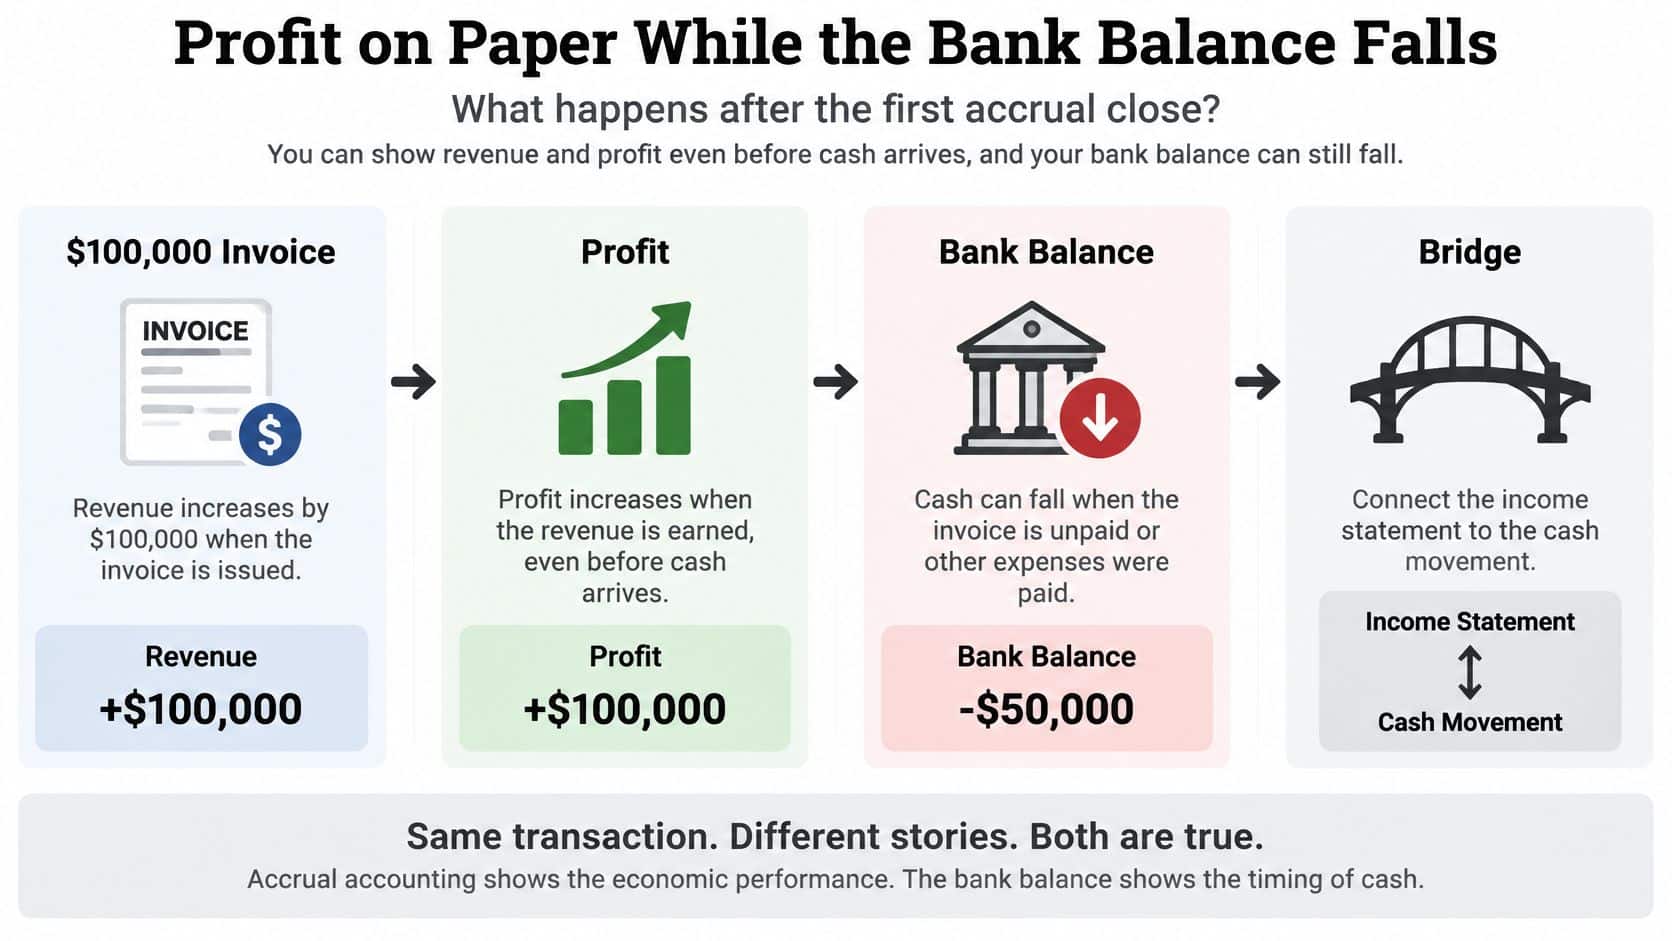
The income statement shows a profitable month, but the bank balance fell. That isn't automatically a bookkeeping error. You may have earned revenue faster than customers paid you.
Sage's explanation of accrual basis accounting distinguishes earned revenue from cash collection; in a $100,000 earned-invoice scenario, revenue and receivables increase while cash collected on that invoice remains zero until payment.
The work date establishes performance. The invoice date starts or documents billing. The cash date determines when that customer's payment can fund payroll or equipment.
Build the bridge from profit to cash
Under the indirect method, an operating cash-flow statement starts with net income and adjusts for noncash items and changes in operating assets and liabilities.
| Balance-sheet movement | Typical adjustment to net income |
|---|---|
| Accounts receivable increases | Subtract, because recognized sales haven't all been collected |
| Prepaid expenses increase | Subtract, because cash paid exceeds the benefit expensed |
| Accounts payable or accrued expenses increase | Add, because recognized costs haven't all been paid |
| Deferred revenue increases | Add, because customer cash arrived before revenue was earned |
| Depreciation expense | Add back, because the expense itself isn't a current cash payment |
For a hypothetical one-month bridge, assume net income of $40,000, receivables rising $100,000, payables rising $25,000, and deferred revenue rising $10,000. With no other adjustments, operating cash flow is negative $25,000, calculated as profit minus the receivables increase plus the liability increases.
That result is before any separately classified debt principal payments or equipment purchases. Interest and other cash-flow classifications should follow the reporting framework.
The diagram highlights the relationship owners need to monitor.
Make spending decisions from the cash schedule
A profitable job can still require financing while you wait for the customer to pay.
Don't approve a hire or equipment purchase from accrual profit alone. Put expected collections, payroll, vendor payments, and debt service on separate weekly lines. A customer's promised payment date deserves a collection assumption, not the same certainty as an already scheduled payroll withdrawal.
An earnings quality analysis helps frame another useful question: how much reported performance is supported by sustainable operations and collectible balances?
Accrual accounting makes performance clearer, but owners can overlook cash risk if they stop at profit. Review the balance-sheet accounts that moved, explain each movement, and assign someone to follow overdue collections. The cash gap becomes a set of actionable balances rather than a surprise.
Work Performed Versus Invoice Versus Cash
Keep the dates in this order: work performed, invoice issued, cash collected. They answer different questions, and none should substitute for another.
A construction revenue disclosure filed with the SEC illustrates the distinction between contract assets arising from performance before billing rights become unconditional and contract liabilities arising from billing or payment ahead of performance.
When work comes before the billing right
Consider a hypothetical crew completing $40,000 of qualifying work before the contract allows the progress invoice. Assuming the revenue-recognition requirements are satisfied, debit a contract asset and credit revenue.
A contract asset represents an earned amount whose collection right still depends on something beyond the passage of time. It isn't automatically accounts receivable. Once the right becomes unconditional, reclassify it to receivables as appropriate.
| Event | What to document | Accounting consequence |
|---|---|---|
| Work performed | Progress evidence and recognition calculation | Revenue and contract asset may increase |
| Billing right becomes unconditional | Contract milestone and invoice record | Contract asset moves to receivable |
| Customer pays | Receipt date and invoice application | Cash increases and receivable clears |
The invoice doesn't create a second sale. It changes the collection status of an amount already recognized.
For construction owners, costs in excess of billing offers related context for reviewing performance and billing gaps.
When cash comes before the work
In the deposit case, the customer pays a retainer before the firm performs the related service. Cash increases alongside a contract liability; revenue waits.
Record any advance invoice separately from the receipt. Then reduce the liability as the business satisfies the relevant performance obligations.
This separation matters for percentage-of-completion jobs, retainage, subscriptions, and change orders. Retainage classification depends on the conditions attached to payment. Subscriptions require a service-period review rather than immediate recognition of the entire advance.
An approved, measurable change order provides stronger recognition support than a field team's expectation of approval. Contract-modification rules can require more judgment, so document enforceability, scope, pricing, and performance before posting.
Keep an open-contract log
| Work to date | Billed to date | Cash to date |
|---|---|---|
| Supported cumulative performance | Issued billings and their contractual basis | Applied customer receipts |
A gap between earned work and billings flags an unbilled amount for classification review. Billings or collections ahead of earned work can indicate a contract liability, but don't add billed and collected amounts together and double-count the same advance.
That log answers both operational questions: why revenue rose without an invoice, and why cash rose without revenue.
Quick Reference Chart and Cross Links
Keep this chart beside the close file. Select the event that happened, then verify the recognition support before posting.
Accrual timing quick reference
| What happened | Record now | Do not record as | Go to |
|---|---|---|---|
| Work earned, customer has not paid | Revenue and receivable when the right is unconditional | New cash income | Core journal entries |
| Cost incurred, vendor not paid | Expense and payable or accrual, unless capitalization is required | Next month's cost | Core journal entries |
| Cash received before the work | Cash and contract liability | Revenue | Work versus invoice versus cash |
| Inventory received on terms | Inventory and accounts payable | Cost of goods sold | Inventory and cutoff |
| Payroll days worked, payday later | Compensation expense and accrual | Next month's payroll | December project walkthrough |
| Profit up and bank balance down | Working-capital bridge | A revenue error by default | Profit versus bank balance |
| Estimate only, no fixed liability | Nothing under these facts | An accrued expense | Recognition tests |
Terms to keep beside the chart
- Accrual: Recognition of earned revenue or incurred costs before the related cash settlement.
- Deferral: Keeping a payment or receipt on the balance sheet until the related expense or revenue belongs in earnings.
- Contract asset: Earned consideration subject to a remaining condition beyond the passage of time.
- Contract liability: An obligation to provide goods or services associated with consideration received or due before performance.
- Economic performance: The tax timing requirement tied to the underlying activity, with specific rules for different obligations.
- Cutoff: The boundary that assigns transactions to the appropriate reporting period.
If an entry lacks support, use the recognition checklist before choosing an account. If an entry is correct but the bank movement seems wrong, reconcile settlements and working capital rather than changing earned revenue to match cash.
For a method-focused reconciliation, the guide to converting accrual to cash helps distinguish timing adjustments from operating performance.
Mark any chart row where your books currently follow the payment date instead of the economic event. Turn those marks into proposed adjustments, attach the supporting records, and have the preparer and reviewer resolve them before finalizing the close.
Pair the Close With a Cash Forecast
This week, take your largest open job and write down its work dates, invoice dates, and cash dates. Post only the accrual entries the recognition tests support, then put collections, payroll, and vendor payments on separate forecast lines.
A 13-week rolling forecast shows cash position every week for the next quarter and is updated weekly as new information arrives. It can show a cash crunch 8 weeks before it hits, giving management time to work on collections, purchasing, or financing.
Turn the worksheet into a decision tool
Use a cash flow forecasting model to connect the close with upcoming commitments. Owners operating in Britain can also use Action Accountants Limited's guidance on forecasting cash flow for UK businesses for locally relevant planning context.
At AmbitionCFO, we build that bridge for founder-led businesses with about $10 million to $100 million in revenue, working alongside their bookkeeper and CPA. For a construction client with $18 million in revenue, our work improved gross margin by 3.1%, reduced WIP delays, and improved cash flow by $640,000.
Clearer job margins help you evaluate delivery while work is underway. A separate weekly cash view helps you decide whether the next hire or equipment purchase is affordable before committing.
AmbitionCFO provides fractional CFO leadership that connects accrual reporting, job profitability, and weekly cash planning. Bring your latest close and a specific 13-week cash question to a conversation with AmbitionCFO, or complete the one-job worksheet before approving your next hire.